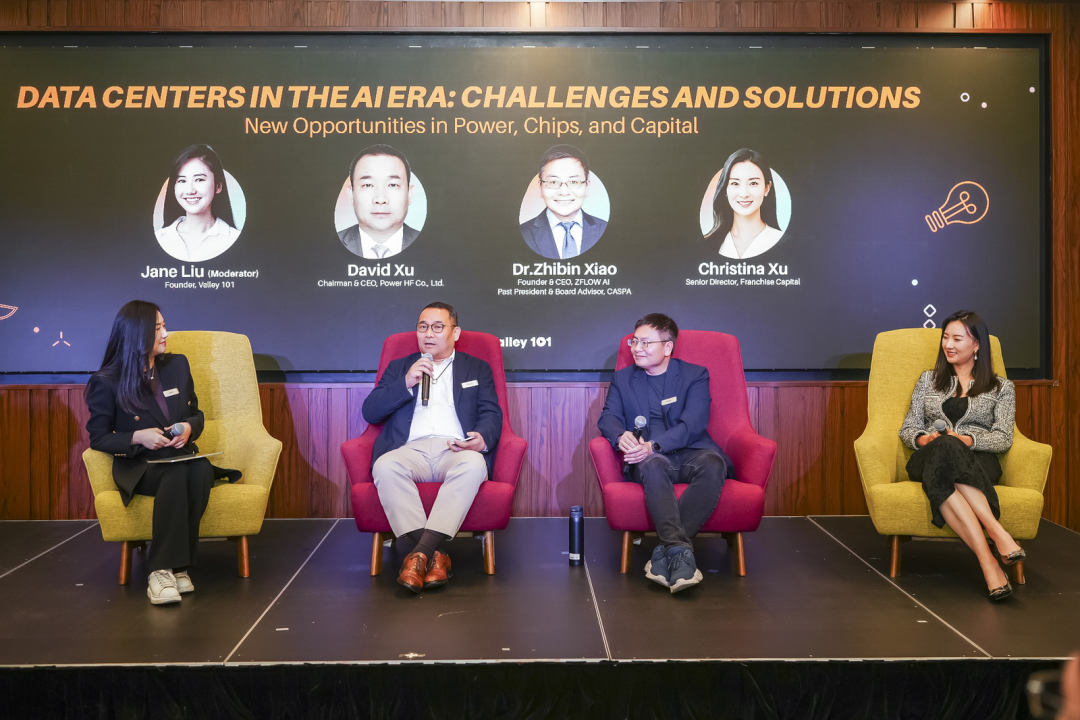
I invest in AI infrastructure. My edge is having operated inside three layers of the stack before I started.
Before my current role, I co-founded an AI company backed by Sequoia-SourceCode Capital, served as acting CFO of an energy-backed AI infrastructure company developing power assets in Texas, and pioneered a new direct enterprise channel at HP Asia from zero to $200M in revenue.
Selected investments: Nebius · Databricks · Anthropic.
Access to unit economics from private infrastructure companies — GPU utilization rates, inference margins, and capex payback periods that never appear in public filings.
On-the-ground visibility into advanced packaging, memory, and optical component supply chains across Taiwan, Japan, and South Korea — the bottlenecks that determine the pace of AI infrastructure buildout.
Having developed power assets for AI infrastructure in Texas and co-founded an AI company, I understand infrastructure economics from the inside — not just the balance sheet.
Two days in Menlo Park with Cursor, Fireworks, Cognition, Sierra and a dozen other AI-native companies. From Token Optimization to Model Routing — why AI's competition is shifting from Capability to Economics, and what it means across Frontier Labs, semis, cloud, and AI software.
A 100-year pattern has governed every major information industry. Wealth flows in three waves: infrastructure first, then compression, then gatekeepers. AI is running the same script.
2025 was a great year for performance. It was also the year I realized how much I had still missed — and why the framework shift AI forces on investors is more uncomfortable than most will admit.
SaaS companies lose market share. AI companies get erased. A note on paradigm velocity, taste, and what kind of VC (and LP) actually survives when the floor disappears overnight.
2026 年最有创业精神的动作,也许就是:加入那个可能让"创业"本身过时的东西。一篇关于范式切换、护城河,与那个最理性的"孤注一掷"的中文长文。